

Cash Advance – Quick Borrow

- 27.00 Reviews
- 4.8
- Downloads
- 10,000+
Our take on Cash Advance – Quick Borrow from Appgk
I approached Cash Advance – Quick Borrow as a finance app for people who want to explore cash-advance and personal-loan offers without beginning with a branch visit. Its purpose is straightforward: help you make an online request for quick cash and review the offers that may follow. That simplicity is useful, but borrowing is never a decision I would make on speed alone. The important question is whether the experience helps you understand what you are considering, especially when you are tired, stressed, using a small screen, or working with limited time.
Developed by TIMECORE Studio, the app is free to install and is listed for Everyone. It runs on Android 7.0 or later, which makes it available to people using older phones as well as newer devices. The current version is 1.0.7. Its finance focus is clear, and the store page shows a 4.8 average from around 948 ratings, with over 10K installs. Those figures suggest that many people have found the basic experience useful, although they do not replace my own advice to inspect every offer carefully before accepting anything.
How the borrowing journey feels on an everyday phone
Readability and navigation when attention is limited
The strongest part of this app is its narrow purpose. I do not have to search through budgeting tools, investment dashboards, or unrelated financial content to understand why I opened it. The central idea is requesting a cash advance or looking at personal-loan offers, so the experience makes sense for someone arriving with one immediate question: “What borrowing options might be available to me?” That focused approach can reduce mental clutter compared with a broader finance platform.
In my experience, focused navigation matters most when the user is already under pressure. A broken appliance, an urgent bill, or a gap between paydays can make even ordinary forms feel difficult. An app that keeps the next step obvious is easier to approach than a website filled with banners, calculators, and several competing calls to action. Here, the value is less about advanced money management and more about keeping the request process understandable.
Best Parts of Cash Advance – Quick Borrow
Things to Keep in Mind About Cash Advance – Quick Borrow
Still, readability in a lending context means more than large-looking labels. I would want to read the complete terms attached to every offer, including the total repayment, timing, fees, and any conditions that affect the cost. A short phrase such as “quick cash” can describe the purpose without explaining the financial commitment. I would therefore treat the first screen as a starting point, not a summary of the decision.
My practical tip is to slow down before moving from an offer to an acceptance step. I would take a screenshot or write down the important figures only after checking that I understand what each figure represents. This is especially helpful if you are comparing the app with a bank, credit union, employer advance, or another lender. A fast request is useful only when the information remains clear enough for a calm comparison.
News and Features Related to Cash Advance – Quick Borrow

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What the app is good at explaining, and what still needs your attention
The app communicates its main job more directly than many general-purpose financial apps. Someone looking for a personal loan does not need to learn a complicated financial system first. That can make the first visit less intimidating for users who are not comfortable with banking language or who rarely apply for credit online.
At the same time, a focused interface can create its own risk: it may encourage a user to think about obtaining money before thinking about repayment. I would have preferred the borrowing journey to be judged by the quality of the explanations around the offer, not merely by how quickly a request can be submitted. Because the app deals with financial products, users should expect to do some of the interpretation themselves.
Don't want to read the full review?
One useful workflow is to use the app for discovery, then move into comparison mode. I would record the amount requested, the amount received, the total amount repaid, the payment schedule, and the consequence of missing a payment if those details are shown. I would then compare that complete picture with an existing bank option or a trusted local alternative. This prevents the app’s convenience from becoming the only factor guiding the decision.
For users with reading difficulties, unfamiliar financial vocabulary, or limited confidence with forms, I would recommend using the app when a trusted person is available to review the details with them. That is not because the app is necessarily difficult; it is because loan language can be consequential even when the screens look simple. A second pair of eyes can catch a misunderstood term before it becomes an expensive mistake.
Screenshots
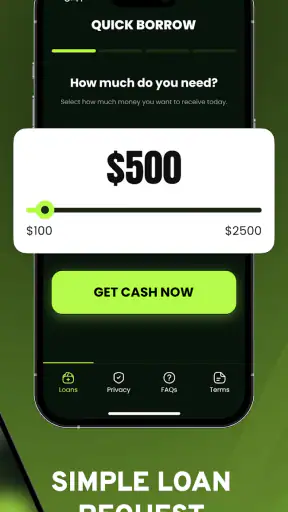
Motor and sensory considerations during a financial request
Cash Advance – Quick Borrow is used on a phone, so the physical experience depends partly on the device. People with limited finger movement may find repeated tapping, scrolling, or typing tiring, particularly if the request asks for several pieces of personal information. I would use the app in a stable position rather than while walking or holding the phone one-handed. That reduces accidental taps and gives me more control over sensitive entries.
Users with tremors or reduced precision can benefit from taking each screen slowly and checking the selected option before continuing. In a financial application, an accidental tap is more serious than in a casual game. I would avoid rushing through buttons simply because the app is designed around quick requests. If the phone supports system-level touch adjustments, magnification, voice input, or a larger display mode, those settings may make the process more comfortable, although their exact behavior depends on the Android device rather than on the app itself.
For people with low vision, text size, contrast, and screen brightness will make a major difference. I would test the app with the phone’s text and display settings adjusted before starting a request. If a label becomes clipped, an amount is hard to distinguish, or a control is too close to another control, I would stop and switch to a larger screen or ask for assistance. Financial information should never be guessed from a partially visible number.
Users with hearing loss are unlikely to need audio to understand the basic purpose of a text-led finance request, but any notification or spoken cue should not be treated as the only way to know what is happening. I would check the visible status of the request inside the app and keep any important confirmation available for later review. Conversely, people who are sensitive to bright screens or visual overload may find a simple finance-focused experience easier than a crowded financial marketplace, provided the text remains comfortable to read.
A less obvious consideration is cognitive fatigue. Someone dealing with an emergency may have trouble comparing similar-looking amounts or remembering whether a figure refers to the advance, a fee, or the total repayment. My approach would be to pause after each major step, read the amount aloud to myself, and compare it with a handwritten note. That small routine is more valuable here than trying to finish in the shortest possible time.
Situational access: when the app fits and when it does not
The most realistic use case is a short-term cash gap that needs attention outside normal office hours. Imagine discovering that a necessary household expense is due before your next paycheck. I could open the app at home, review whether any offer is available, and compare the repayment obligation with my next income. The convenience is meaningful because I can begin online rather than arranging a branch appointment.
That scenario does not automatically make borrowing appropriate. If repayment would leave me short for rent, food, utilities, or medication, I would not use the app merely because the request feels easy. I would first check whether delaying a nonessential purchase, contacting the bill provider, using an employer resource, or asking a trusted person provides a safer solution. The app can help present an option; it cannot make an unaffordable repayment plan affordable.
The app may also suit someone who wants to explore loan possibilities privately. A person who feels uncomfortable discussing a temporary cash problem in person may appreciate beginning on a phone. Privacy, however, requires practical care. I would avoid applying on a shared device, public Wi-Fi, or a phone that other people can unlock. I would also make sure I know where the device stores notifications and whether another person could see financial messages on the lock screen.
For users with unreliable internet access, situational access becomes less predictable. An online request depends on being able to load screens and submit information successfully. I would not begin the process immediately before a deadline or while travelling through an area with poor connectivity. If the connection fails, I would avoid repeatedly submitting the same request until I had checked whether the first attempt went through.
Older Android users may appreciate the broad operating-system compatibility. The minimum requirement of Android 7.0 means the app is not limited to the newest phones, which can matter for people who cannot afford frequent upgrades. However, an older phone may have a smaller display, slower performance, or less comfortable typing experience. Compatibility makes installation possible; it does not guarantee that every device will feel equally easy to use.
Remaining barriers before anyone accepts an offer
The biggest barrier is not navigation. It is the pressure created by urgent borrowing. When someone needs money quickly, the promise of speed can overshadow the cost of repayment. I would like every user to remember that a convenient request is still a financial commitment. The app should be treated as a tool for reviewing possibilities, not as proof that taking the money is the right answer.
Another barrier is comparison. A user may see an offer and assume it is the best available option because it appears inside the app. I would not make that assumption. I would compare the complete repayment amount and schedule with alternatives, and I would check whether the payment date matches my actual income cycle. A loan that looks manageable on one date can become difficult if the timing is wrong.
People who are not fluent in financial terminology may need extra support. I would be cautious with words that sound similar but describe different things, such as the amount requested, the amount deposited, and the total repayment. If an explanation is unclear, I would not rely on an online search result alone; I would look for an authoritative explanation or ask a qualified financial adviser. The app’s speed cannot compensate for a term I do not understand.
There is also a human-access barrier for users who need alternative communication or assistance. Some people may prefer a phone conversation, paper documents, or in-person guidance because typing on a mobile device is difficult. In that situation, a traditional bank, community lender, or local advice service may be a better fit. I would choose the channel that lets me understand the commitment, even if it takes longer.
I would also skip this app if I were looking for a full financial-management system. It is not the tool I would choose for tracking spending, building a long-term budget, monitoring investments, or organizing several accounts. A banking app or dedicated budgeting app is more suitable for those tasks. This product makes sense when the immediate need is to explore a cash advance or personal-loan request, not when the goal is broader financial planning.
Who should use it, and who should choose another route
I see the best fit as an adult who understands that the app presents borrowing possibilities, can read and compare the terms, and has a realistic repayment plan. The Everyone content rating makes the app broadly listed for general audiences, but that should not be confused with every borrowing option being suitable for every person. Financial responsibility still depends on circumstances, income, existing obligations, and the details of the individual offer.
I would recommend it as a convenient first stop for someone comfortable completing an online request and wanting to investigate options from a phone. It can also be useful for a person who values a focused interface over a large banking app with many unrelated features. The free installation removes an upfront app cost, which is helpful when someone is already managing a tight budget, although the financial product being considered must be judged separately from the app’s installation price.
I would advise caution for anyone who is already juggling several repayments, has irregular income, or is borrowing to cover another loan. In those situations, a nonprofit debt adviser, credit counselor, bank, or community organization may offer more useful guidance than another fast application. If the main need is a lower monthly burden rather than new cash, debt advice and restructuring options deserve attention before a new request.
For accessibility, I would describe the app as potentially approachable rather than universally accessible. Its focused purpose and support for an older Android release are practical strengths. The remaining experience depends on screen size, touch accuracy, reading comfort, connection quality, and how clearly the user can interpret financial terms. Those factors should guide the choice of device and whether another person should be present.
My inclusive verdict after weighing convenience against care
Cash Advance – Quick Borrow does one specific job and presents a simple reason to open it: explore a cash advance or personal-loan request online. I like that focused direction, the free entry point, and the ability to use it on Android devices starting with version 7.0. TIMECORE Studio has created something that may feel less intimidating than a full banking platform for users who need to investigate a short-term option from a phone.
My reservation is equally clear: speed must not become a substitute for understanding. The app is most helpful when I use it as a comparison and information step, write down the full repayment details, and check whether the payment schedule fits my real budget. It is less suitable when I am desperate, unable to read the terms comfortably, or hoping that a new loan will solve an existing debt problem.
Overall, I would recommend trying it only with a deliberate plan. Use accessibility settings that make the screen comfortable, avoid rushed submissions, protect your privacy, and involve a trusted adviser when the language or numbers are difficult. The most inclusive way to use this app is to make the process slower than its promise of quick cash. That approach preserves its convenience while giving different users a fairer chance to make an informed decision.
Cash Advance – Quick Borrow FAQ
What is Cash Advance – Quick Borrow, and how does it work?
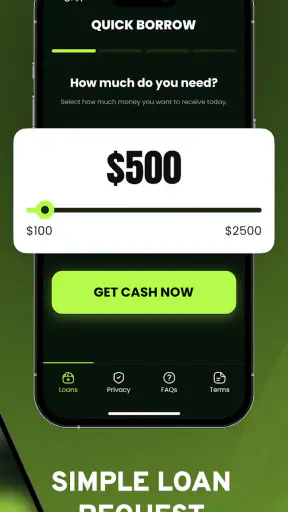
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account, you generally provide personal and financial information, choose an available advance amount, and submit a request for review. Approval, funding speed, repayment terms, and availability can vary depending on your location, credit profile, income, and the provider’s eligibility requirements.
Is Cash Advance – Quick Borrow available to everyone?
No. Access is not guaranteed for every applicant. Eligibility may depend on factors such as age, residency, employment or recurring income, banking information, identity verification, and the lending rules applicable in your region. Before applying, review the app’s current availability and requirements carefully. Some users may receive a smaller amount, different terms, or no offer after the application is assessed.
How much does it cost to use Cash Advance – Quick Borrow?
The total cost can include interest, service charges, subscription fees, origination fees, late-payment charges, or other amounts depending on the offer and your location. Do not rely only on the advertised advance amount. Read the agreement and disclosure screen before accepting, paying close attention to the annual percentage rate, repayment total, due date, and any recurring membership charges. Only proceed if the full cost is clear.
How quickly can I receive money through the app?
The app may present quick funding as one of its main benefits, but delivery is not always immediate. Processing can depend on approval time, identity checks, bank compatibility, weekends, holidays, and whether an additional express-transfer fee applies. Even after approval, your bank may require extra time to post the funds. Check the estimated arrival time and associated charges before confirming the request.
What should I know about repayment and personal data before applying?
Before submitting an application, make sure you understand exactly when repayment is due and how the payment will be collected. Missing a payment may lead to additional fees, failed-payment charges, collection activity, or negative consequences depending on the provider and local law. Also review the privacy policy to learn how the app handles banking, identity, contact, and financial information, and grant only permissions you consider necessary.











